Battery storage arbitrage has moved from a niche trading tactic to the single biggest source of storage value in 2026. France has already logged around 800 hours of negative or zero electricity prices this year — an all-time record — and Germany saw negative prices in 10% of all hours in the first eight months, up from 5% in 2024 and 3% in 2023. For a battery owner, those aren’t market failures; they are the cheapest charging windows of the decade. The catch: the same volatility that makes storage valuable is drawing so much capital that spreads will narrow — so how you specify the asset decides whether it earns.
Want storage that earns across arbitrage, peaks and grid services?
Send us your market, tariff and load profile — we return a sized, certified LFP storage package built to stack revenue instead of betting on one price line.
Why Battery Storage Arbitrage Broke Records in 2026
The 2026 spread story is a European one first. France recorded roughly 800 hours of negative or zero prices by early October, against 359 hours in all of 2024 and 147 in 2023 (RTE data, via pv magazine). The average daily spot spread reached €214/MWh — a level not seen since 2022 — swinging between average lows of €32/MWh and highs of €247/MWh, with day-ahead prices averaging €143/MWh year to date. The driver was supply, not demand: nuclear availability fell 3.7 GW year on year, wind 2.3 GW and hydropower 1.5 GW after a dry summer, while solar added 1.8 GW and gas 1 GW. On 1 May 2026 the French spot market printed −€498/MWh.
That is the raw material of arbitrage. Storio Energy’s September price monitor shows what it is worth in practice: a 1 MW/2 MWh battery charging at an average €73/MWh and discharging at €232/MWh earned 135% more spot revenue than a year earlier, and its 2026 cumulative revenue is 50% above 2025 and more than double 2024. Germany tells the same story from the other direction, where negative-price hours have roughly tripled since 2023.
Battery Storage Arbitrage in 2026: The Spreads in Numbers
Four markets, four different ways the same mechanism shows up:
| Market | Key 2026 metric | What it means for a battery |
|---|---|---|
| France | ~800 h of negative/zero prices; daily spread ≈ €214/MWh | Charge near €73/MWh, discharge near €232/MWh (Storio, Sept 2026) |
| Germany | Negative prices in 10% of hours (5% in 2024, 3% in 2023) | Cheapest charging windows in a decade — if the asset is merchant-ready |
| Great Britain | First FCA-regulated BESS revenue index hedged (Statkraft & SSE) | Storage revenue can now be priced, sold and hedged like an asset class |
| Australia (NEM) | 59 grid batteries earned AU$88.91m in Q3 2026, +57% QoQ | Merchant energy + FCAS revenue is compounding, not stalling |
| India | ~50 GWh BESS approved; 45–50 GWh targeted for FY2027–28 | A new commercial revenue stack is opening outside Europe |
The Cannibalisation Trap: Everyone Is Buying Storage Now
Record spreads are a magnet for capital, and capital is arriving fast. Germany’s grid operators have now approved storage connection requests with a combined capacity greater than that of all the country’s pumped-storage plants. Statkraft’s Claus Urbanke is blunt about the consequence: investors today are ‘catching a falling knife’ — spreads will narrow as more batteries chase the same hours. Volue’s Helmut Spindler puts it even more directly: ‘the easy money is over.’ BloombergNEF expects UK operators to need progressively more complex trading strategies as the market saturates, and CRISIL Ratings warns that roughly 12 GWh of India’s under-construction BESS capacity — about 21% of the analysed pipeline — could deliver weak returns.
None of that makes storage a bad investment. It makes single-revenue-line storage a bad investment. A project underwritten on one ancillary service, or on last year’s spot spread extrapolated forward, is precisely the project that cannibalisation punishes first.
Revenue Stacking Is How Storage Gets Paid in 2026
The mature answer is revenue stacking — one battery, several coordinated income streams that share the same MW, MWh and state of charge. Frontier Economics’ 2026 study for Germany’s BVES finds that 4-hour systems are economically viable today precisely because they stack wholesale arbitrage with frequency containment and automatic reserves and capacity payments, and it projects system CAPEX falling below €150/kWh by 2030. In Britain, the March 2025 T-4 Capacity Market auction awarded 15-year agreements to about 1.8 GW of new battery capacity — more than 80% of all new-build agreements — including roughly 880 MW of four-hour-plus batteries versus just 123 MW in the previous auction. And in September 2026 Statkraft and SSE completed what they describe as the first financial swap tied to a regulated BESS revenue index, covering wholesale, balancing, frequency response, reserve and capacity market income in one hedged benchmark.
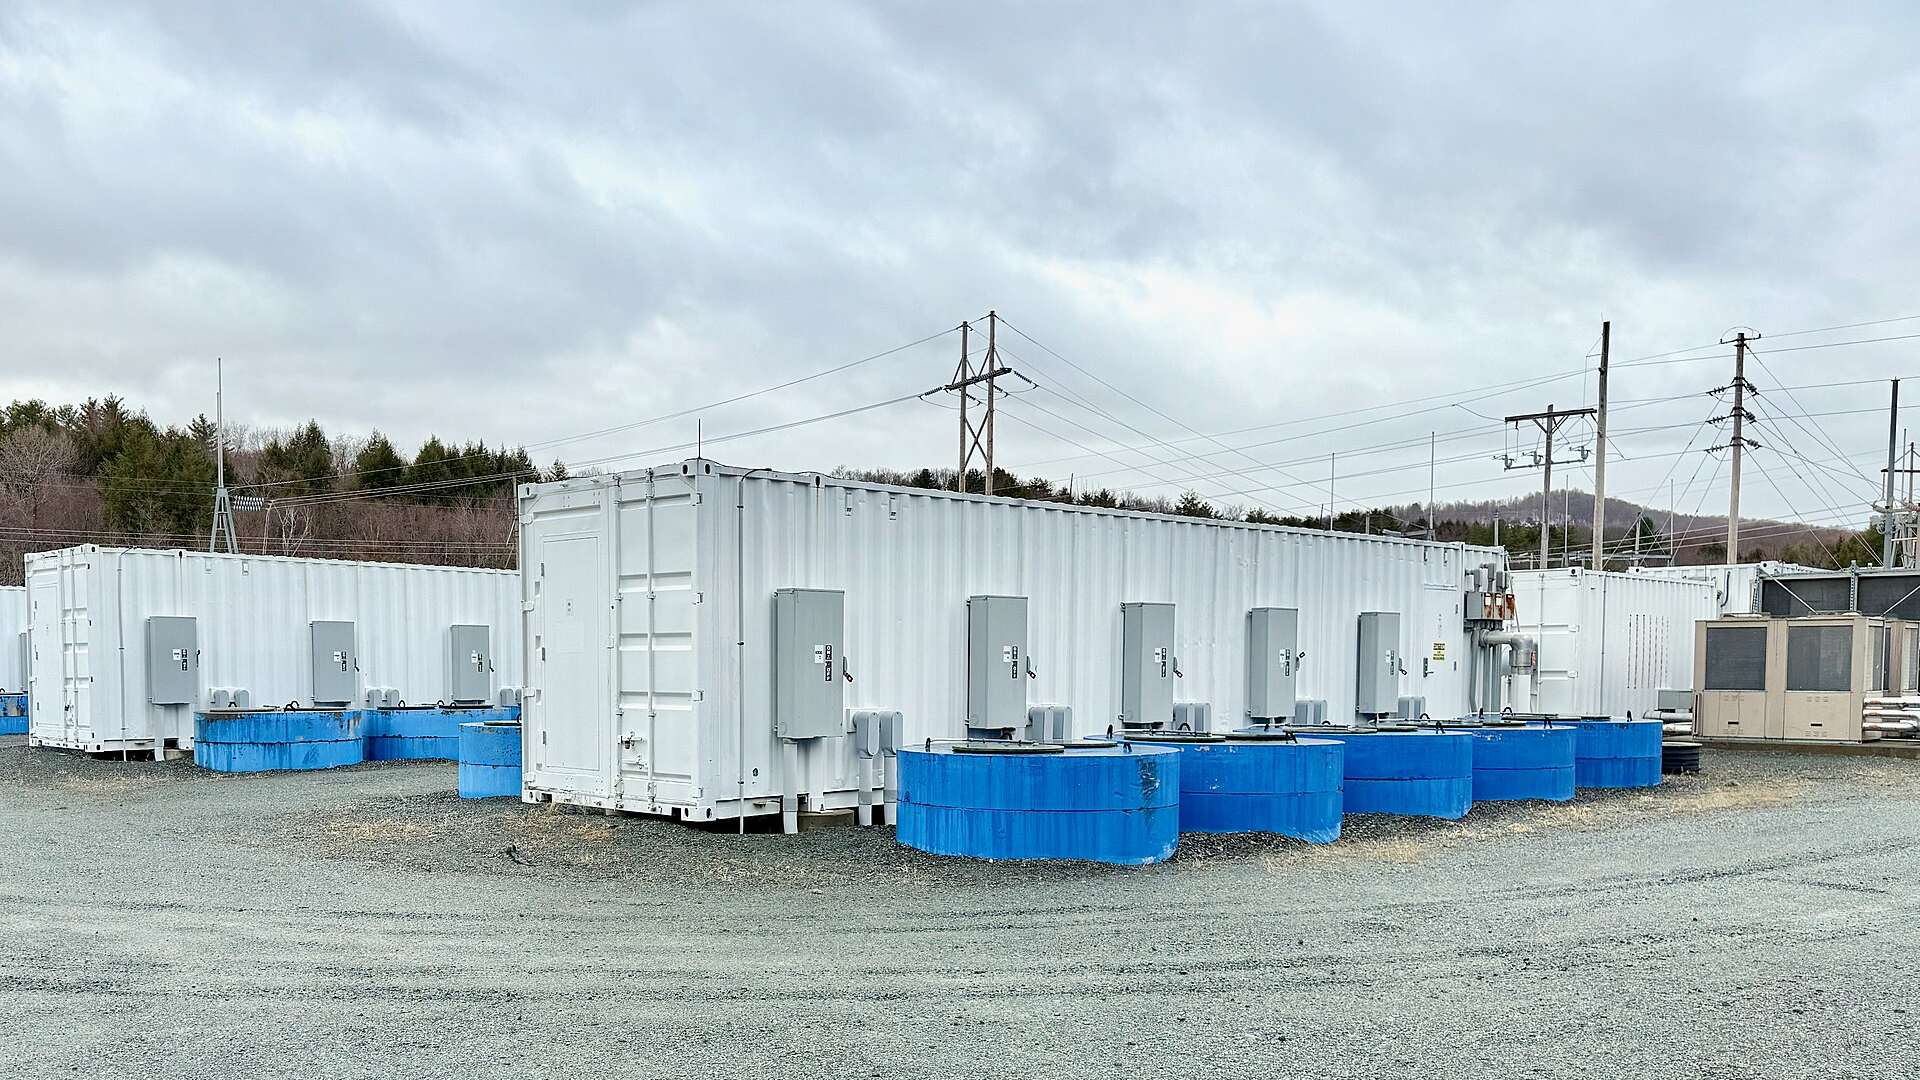
The tooling has caught up. Storage is now something you can finance, hedge and optimise as infrastructure, not just trade. That is the shift buyers should be pricing into their specifications — starting from an containerized LFP BESS designed for deep daily cycling rather than a single application.
What Record Spreads Mean for Buyers Outside Europe
Most emerging markets do not yet have liquid day-ahead trading, but the same value mechanism appears under different names: demand-charge reduction, solar shifting and diesel displacement. In India, an illustrative 20-site commercial portfolio with a 10 MW/20 MWh battery against a 30 MW peak shows gross annual benefits of roughly ₹1.5–3.5 crore from demand management, ₹2–4 crore from arbitrage and peak-import avoidance, ₹1.5–2.5 crore from diesel avoidance and further gains from solar spill reduction — a combined ₹6.1–12.6 crore, with payback commonly landing in 12–30 months (Growthifye, 2026).
The pattern repeats across the emerging markets NEGUP serves. In Morocco, a 5-hour battery integrated with industrial solar cuts the site’s peak-hour electricity bill by about 25% over a 25-year life. In India, hybrid storage paired with diesel generators cuts fuel consumption by 40–80% depending on load profile. In every case the battery arbitrages the gap between cheap generation and expensive peak supply — the same trade in a different wrapper.
How to Specify Storage That Earns More
Six specification choices decide whether an asset can capture these spreads:
- Duration: four hours is the 2026 economic standard for stacking; go shorter only where value is concentrated in a narrow evening block.
- LFP chemistry: 6,000+ cycle life at 80% depth of discharge is what makes daily arbitrage cycling pay over a 15–20 year life.
- Liquid cooling: tighter cell temperatures improve round-trip efficiency and extend life 20–30%, which directly lifts revenue per cycle.
- Grid-forming PCS and a fast EMS: the ability to dispatch continuously across day-ahead, intraday, balancing and imbalance is now the difference between average and top-quartile revenue.
- Degradation-aware dispatch: every cycle has a wear cost; a system that prices it in avoids burning life for thin spreads.
- Modular headroom: start at the contracted grid capacity and add blocks as the revenue stack matures.
On cost, the hardware is not the constraint: Ember puts turnkey utility-scale storage near US$125/kWh, China’s 314 Ah energy-storage cells quoted around RMB 0.367/Wh in late September 2026, and battery-grade lithium carbonate sat near RMB 122,800/tonne. For commercial and industrial sites the equivalent building block is a modular commercial and industrial ESS, while the largest projects start from a utility-scale BESS platform. For distributed buyers stacking self-consumption with backup, a residential ESS covers the same logic at smaller scale.
The Bottom Line for 2026 Storage Buyers
The record spreads of 2026 are a genuine opportunity, and also a warning. Negative-price hours and wide daily spreads have made storage the most valuable flexible asset on modern grids — and have simultaneously guaranteed that spreads will narrow as deployment accelerates. The buyers who do well will not be those who chase last year’s price, but those who specify storage to stack revenue from day one: the right duration, durable LFP cells, liquid cooling, grid-forming controls and a dispatch strategy that prices every cycle. Hardware cost is at a historic low and the revenue toolkit is maturing fast. What remains is engineering discipline — best settled before the purchase order, not after.
Frequently Asked Questions
Is battery storage arbitrage still profitable in 2026?
Yes — but the mix has changed. Volue’s head of trading, Helmut Spindler, says plainly that ‘the easy money is over’: the early strategy of parking a battery in frequency response has saturated in Germany and the UK. What still pays is combining wholesale, continuous intraday, balancing and imbalance, and shifting capacity between them through the day. In France, Storio Energy reports a 1 MW/2 MWh battery charged at an average €73/MWh and discharged at €232/MWh in September 2026, running about 1.5 cycles a day.
How much can a storage asset actually earn in 2026?
It depends heavily on market and duration, but the direction is up. Australia’s National Electricity Market saw 59 grid-scale batteries earn about AU$88.91 million in gross energy and FCAS revenue in Q3 2026, a 57% jump on Q2 (Daily Energy News). Energy Vault’s 125 MW/1 GWh Stoney Creek project in New South Wales combines a 14-year Long-Term Energy Service Agreement with merchant upside for roughly A$25–30 million a year. In India, an illustrative 20-site, 10 MW/20 MWh commercial portfolio shows a gross annual benefit range of ₹6.1–12.6 crore.
Will arbitrage spreads collapse as more batteries are built?
Partly, and buyers should assume it. Statkraft’s Claus Urbanke describes today’s German market as investors ‘catching a falling knife’ — healthy spreads now, narrowing later through cannibalisation. Germany’s grid operators have already approved storage connection requests exceeding the country’s entire pumped-hydro capacity. CRISIL Ratings warns that roughly 12 GWh — about 21% of India’s under-construction BESS pipeline — risks weak returns. The response is not to avoid storage but to specify it for revenue stacking and, where available, contract or hedge a floor.
What duration should I buy for arbitrage and peak shaving?
Four hours has become the 2026 economic standard. The Frontier Economics study for Germany’s BVES finds 4-hour lithium-ion systems are viable on revenue stacking at current prices, with the market needing 15 GW/57 GWh by 2030. Where the value is concentrated in a short evening block, a 2–3 hour system can win on capital efficiency; in Indian commercial solar-plus-storage, viable projects commonly land at 15–35% battery power relative to solar AC capacity with 2–4 hours of duration. Energy is cheap now, so upsizing duration is cheaper than retrofitting it later.
What does storage hardware cost in late 2026?
System prices continue to sit near record lows. Ember’s indicative benchmark is about US$125/kWh for turnkey utility-scale storage, and global BESS costs have fallen roughly 95% since 2010. On China’s cell market, 314 Ah energy-storage cells quoted around RMB 0.367/Wh in late September 2026, with 100 Ah cells near RMB 0.420/Wh and battery-grade lithium carbonate at about RMB 122,800/tonne. That cost base is exactly why the revenue side, not the hardware line, now decides whether a project clears its hurdle rate.
Related insights
- The 5XX Era: How 500Ah+ Storage Cells Are Rewriting Battery Assembly Economics
- Solar Power Station Efficiency Tips
- Global BESS Surge: 18 GWh Online in July as Europe Goes Continental
WhatsApp +86 15307690902 | rain@negupgroup.com