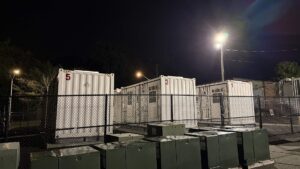
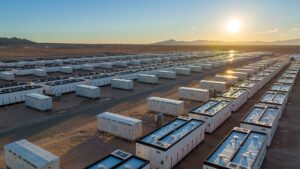
The Singapore BESS target moved on 26 October 2026. The Energy Market Authority published an Energy Infrastructure Plan committing the city-state to “just over 1GWh” of storage by 2030, against roughly 350MWh operating today, and opened a consultation on how to get there that runs to 27 January 2027 (Energy-Storage.news). Small by the standards of Texas or Shandong. It is also the first time an ASEAN market has put a gigawatt-hour figure and a consultation closing date in one document, and that pairing is what suppliers should read.
Quoting Into a Reserve Market? Start With the C-Rate.
Send the MW, the MWh and the grid code you must comply with. We return a container count, a footprint and a cooling specification for a tropical site.
What Did the EMA Plan Actually Commit To?
Six commitments sit inside the five-year plan and only one is about batteries. Storage: just over 1GWh by 2030. Solar: 4GWp by 2035, raised from 3GWp by 2030, with about 2.3GWp installed. Gas: the fleet grows around 26% from 12GW. LNG: regasification rises from 10 million tonnes a year to 15Mtpa by 2030. Networks: SG$5.3 billion, about US$4.14 billion, of transmission and distribution spend across 2025 to 2029, seven new substations by 2031 and a 2,000km extension of the transmission system. Imports: a second interconnector with Peninsular Malaysia at up to 2GW by the end of the decade, against 1GW bidirectional today (EMA announcement).
| Plan item | Today | Target | What it does to storage demand |
|---|---|---|---|
| Energy storage | ~350MWh operating | Just over 1GWh by 2030 | About 2.9x the installed base in five years |
| Solar PV | ~2.3GWp installed | 4GWp by 2035 | More variable supply raises the value of fast flexibility |
| Peak demand | 8.6GW in August 2026 | 9.9GW to 13GW within five years | A thinner reserve margin prices capacity, not energy |
| Gas fleet | 12GW | About 26% larger | Storage competes with peakers for the same reserve role |
| LNG regasification | 10Mtpa | 15Mtpa by 2030 | Cheap fuel means storage must win on speed, not fuel savings |
| T&D network | — | SG$5.3bn, 2025–2029; 7 substations | New substations are where grid-scale batteries interconnect |
Why the Singapore BESS Target Is Small but Load-Bearing
Do the arithmetic before getting excited. Going from about 350MWh to just over 1,000MWh is roughly a 2.9x increase in installed energy, which sounds like a boom and is really one medium-sized programme. Against peak demand of 8.6GW in August 2026, 1GWh is about seven minutes of peak output. Nobody runs Singapore on that.
Which is why the specification matters more than the volume. A grid that buys storage in minutes rather than hours is buying reserve, and a reserve market pays for availability in megawatts. That pushes buyers toward higher C-rates, tighter round-trip efficiency and grid-forming capability, and away from the cheapest long-duration block. A 4-hour system optimised for arbitrage is the wrong asset here; start with the grid-forming and grid-code requirements, not the price sheet.
The Demand Curve Behind the Target
Peak demand was 8.6GW in August 2026. The EMA forecasts 9.9GW to 13GW within five years, driven by semiconductor manufacturing, data centres and electrification including EVs. Take the top of that range and the system needs up to 4.4GW of new firm capacity in five years, on an island with almost no land and no wind.
That is the real argument. Not that batteries beat gas per megawatt-hour, but that a battery can be permitted and energised inside the time it takes to site a turbine, and can sit on a substation plot. The plan says as much by pairing the storage target with seven new substations: the batteries follow the copper. Globally the same logic is why BloombergNEF expects deployments to grow 45% in 2026 and reach 3.1TW cumulative by 2036 (BloombergNEF forecast).
Where the Storage Will Sit
The precedent is already on Jurong Island. Sembcorp’s 200MW/285MWh LFP system there reached commercial operation in 2023, two years ahead of the 200MWh target the EMA had set for 2025. Read 1GWh against that single asset and it is roughly 3.5 times the Jurong Island system: not one mega-project, but three or four assets of that class plus distributed units behind substations.
Land is the binding constraint and it shapes the product. A 200MW/285MWh installation is a sub-1.5-hour asset; more megawatt-hours on the same plot means taller racks or denser cells. That is the case for containerized BESS platforms over purpose-built buildings: the container is the permit, the footprint and the shipping unit at once. For front-of-meter work the utility-scale range carries the higher DC/AC ratios; behind the meter at a data centre or fab, the commercial and industrial ESS line is the shorter path.
What the Consultation Window Means for Suppliers
The target is not the deliverable; the consultation is. Alongside the plan the EMA published an Energy Storage Systems Vision and Industry Consultation Paper, open until 27 January 2027, seeking views on technologies, business models and projects and on changes to existing rules (EMA consultation). The agency said it will widen access to market information and review the rules that govern storage.
For a supplier that is a timetable, not a formality. Rules settled in the first half of 2027 set the revenue stack the 2028 to 2030 build underwrites against, and the equipment specification follows the revenue stack. Compare it with a mature capacity market: in PJM the 2026/2027 base residual auction cleared at US$329.17 per megawatt-day, the FERC-approved cap, and that number, not a hardware quote, is what a storage owner underwrites. Singapore has no PJM equivalent yet, which is precisely what the consultation is about.
How to Read 1GWh as an Order Book
Convert the target into factory units. Just over 1GWh is 1,000MWh and change. At the 285MWh-to-200MW ratio of the Jurong Island system that is roughly 700MW of PCS and power electronics across the programme. At a 2-hour duration it is about 500MW; at 4 hours, 250MW. The gap between those two numbers is the entire commercial argument, and it is settled by whether revenue comes from reserve or arbitrage.
Then split the programme. Part of the 1GWh will be grid-scale and tendered; part will sit behind the meter at data centres, the counterparty type Singapore respondents rated most important for storage contracts in a DLA Piper survey of Japan, Singapore and Australia. Those are different products with different lead times, and one container platform will not win both.
What to Specify for a Tropical, Land-Constrained Site
Singapore is a hard environment for a battery: humidity near saturation, a diurnal range that never gives cells a cool night, and a fire code that assumes an occupied building next door. Three points decide whether a container survives ten years: thermal management sized for ambient rather than datasheet, an enclosure rating that matches washdown and salt-laden air, and a fire detection and suppression design the authority having jurisdiction will accept.
The fourth is serviceability. An island market with one port and no adjacent manufacturing base punishes any design needing a specialist crew for routine work. Ask for the maintenance task list and the spare-parts list before the price. Our ESS integration and quality control process is built around that constraint, and the 2026 containerized BESS cost breakdown shows what the enclosure and thermal package add.
The useful next step is a sizing sheet, not a brochure. Send the MW, the MWh, the duration you are paid for and the grid code you must meet, and we return a container count, a footprint and a cooling specification for a tropical site. Start from the battery energy storage system range for the architecture, the containerized platforms for fast deployment, or the 215kWh commercial and industrial container unit behind the meter. More market context sits in our storage news archive.
What is Singapore’s new battery storage target?
The Energy Market Authority set a target of just over 1GWh of storage deployments by 2030 in its Energy Infrastructure Plan of 26 October 2026, against about 350MWh operating today. That is roughly a 2.9x increase in installed energy over five years.
Why does 1GWh matter on a grid peaking at 8.6GW?
It is small in energy, about seven minutes of peak output, but significant in capacity. Peak demand is forecast to rise from 8.6GW in August 2026 to 9.9GW to 13GW within five years, so value sits in reserve rather than bulk shifting. That favours higher C-rates and grid-forming capability.
When does the EMA consultation close?
The Energy Storage Systems Vision and Industry Consultation Paper is open until 27 January 2027. It covers technologies, business models, projects and rule changes, plus wider access to energy market information.
How many containers does 1GWh need?
Convert through the local precedent. Jurong Island is 200MW/285MWh, so 1GWh is about 3.5 times that asset, or roughly 700MW of PCS at the same ratio. At 2 hours the programme is about 500MW; at 4 hours, about 250MW.
What should a tropical site specification include?
Thermal management sized for year-round ambient, an enclosure that survives humidity and salt-laden air, fire detection and suppression the authority will accept, and a maintenance task list short enough for a crew that has to fly in.